Part of the IQ-EQ series: Raising institutional capital in Asia-Pacific
At a glance
Why Singapore matters
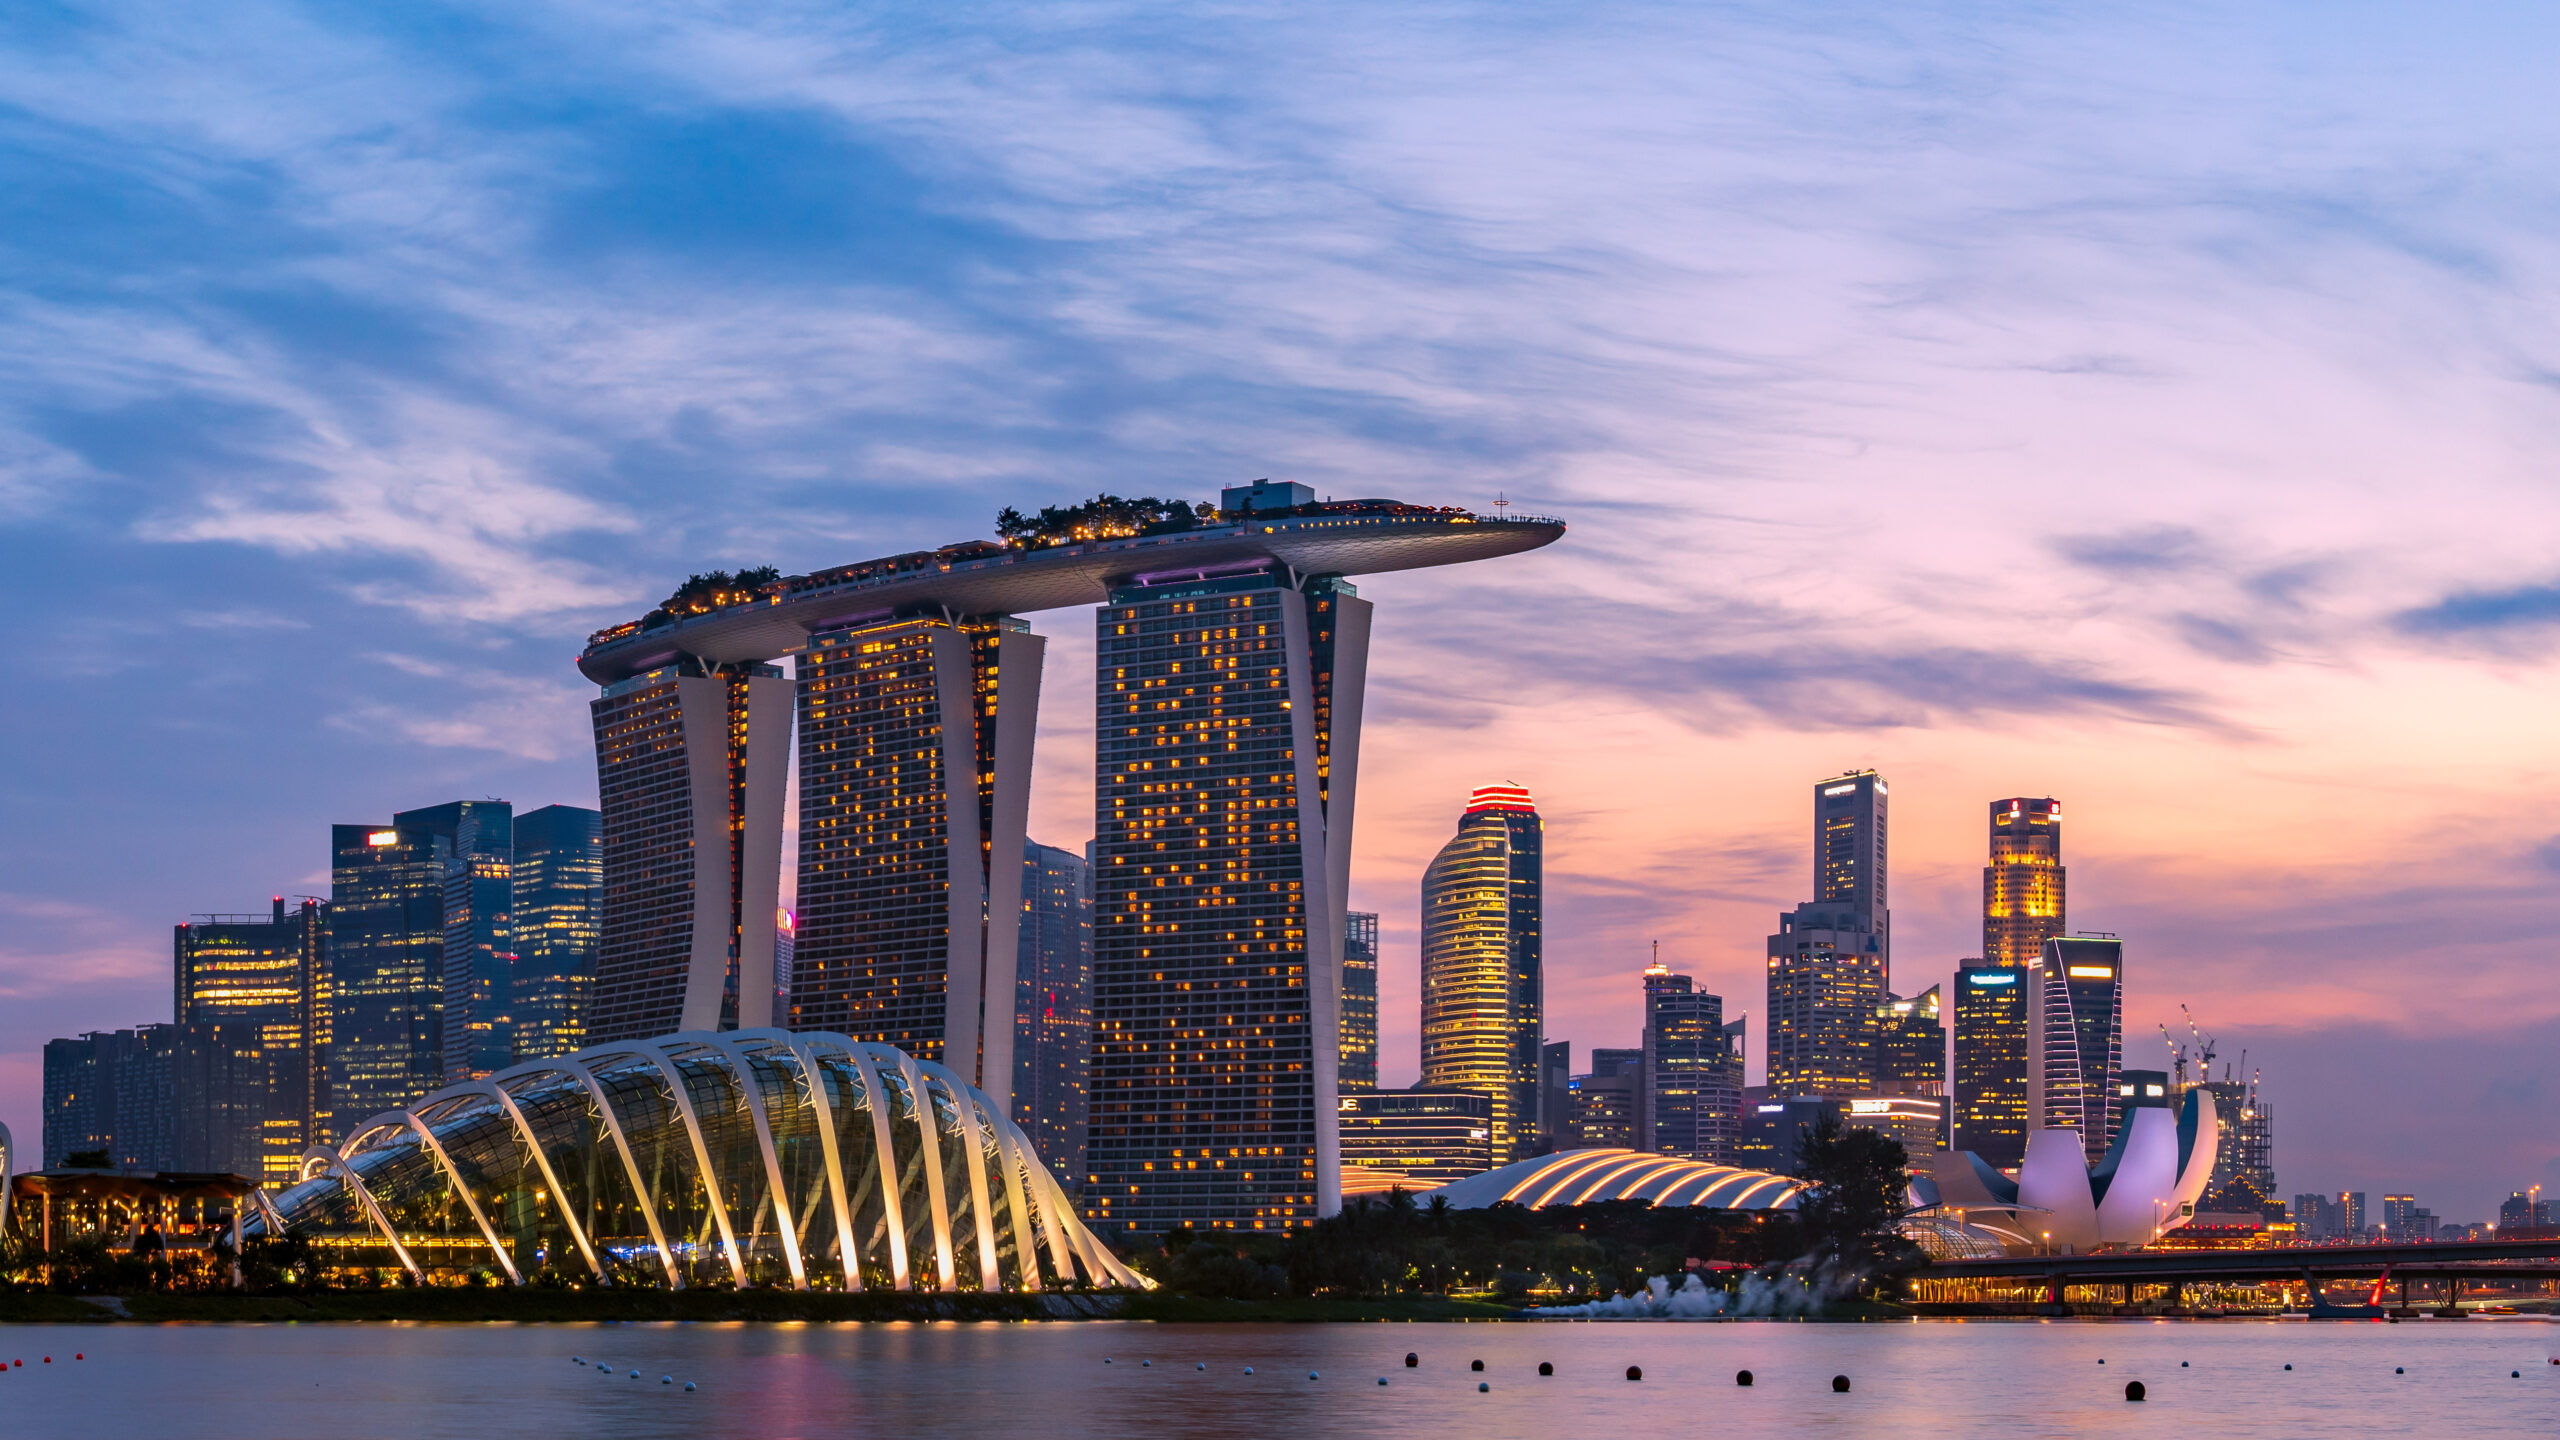
Singapore is often the first jurisdiction considered by global alternative investment managers entering Asia.
Unlike many regional financial centres, Singapore offers access to multiple pools of capital through a single ecosystem. Institutional investors, government-linked allocators, global insurers, private banks, family offices and external asset managers all maintain substantial operations in the city-state.
The combination of capital availability, regulatory stability and international connectivity has helped position Singapore as Asia’s premier asset management hub.
For many U.S. managers, Singapore serves two strategic functions:
- It provides direct access to some of Asia’s largest institutional allocators
- It acts as a gateway to broader regional capital, with many investment decisions for Southeast Asia, North Asia and global portfolios being coordinated or influenced from Singapore-based investment teams.
Singapore’s institutional investor landscape
Sovereign and government-linked allocators
The institutional investment landscape is dominated by several globally significant state-linked investors:
GIC manages Singapore’s sovereign reserves and is widely regarded as one of the world’s largest and most sophisticated institutional investors. The organisation allocates across public and private markets globally and maintains relationships with a broad range of alternative investment managers.
Temasek differs from traditional sovereign wealth funds in that it operates as a direct investment company rather than a conventional fund manager. It maintains a highly active ownership approach and significant global investment exposure across both public and private markets.
The MAS serves as Singapore’s central bank and financial regulator, while also managing a substantial pool of official foreign reserves. Through its reserve management activities, MAS invests across global fixed income, currency and other international markets, and works with a range of external investment managers. Its scale, sophistication and long-term investment horizon make it an important participant within the institutional allocator landscape.
Singapore also hosts a range of government-linked investment vehicles and fund-of-funds programmes that allocate capital both domestically and internationally. These institutions contribute to Singapore’s position as one of Asia’s most influential centres for institutional capital deployment.
Private banking remains a critical distribution channel
While sovereign and government-linked institutions often receive significant attention, private banks remain one of the most important gateways to capital in Singapore.
Many ultra-high-net-worth investors access private markets through:
- Feeder structures
- Approved fund platforms
- Discretionary portfolio mandates
- Managed account programmes
As a result, managers frequently discover that securing platform approval from private banks can have a greater impact on fundraising outcomes than direct engagement with individual investors.
The MAS has also encouraged broader participation in alternative investment products, including evergreen and semi-liquid fund structures distributed through banking channels. This trend is creating new opportunities for managers capable of satisfying the due diligence requirements of private bank gatekeepers.
Family offices: a growing but evolving market
Singapore’s family office sector has expanded rapidly over the past decade.
However, the sector has undergone significant regulatory evolution following several high-profile anti-money laundering investigations.
The government has introduced more prescriptive requirements concerning:
- Ownership structures
- Onshore presence
- MAS notifications
- Annual reporting obligations
- Source of wealth verification
- Source of funds assessments
- Enhanced due diligence on connected persons
As a result, family offices have become increasingly institutional in their governance expectations and operational requirements.
While Singapore remains one of the leading family office destinations globally, managers should not assume access to capital is informal or lightly regulated.
Understanding Singapore’s licensing framework
Fund marketing is generally a regulated activity
Singapore regulates fundraising activity primarily through the Securities and Futures Act (SFA).
A Capital Markets Services (CMS) licence is generally required to carry on dealing in capital markets products, including fund interests. Activities that may trigger licensing requirements include:
- Marketing funds
- Offering fund interests
- Arranging subscriptions
- Acting as a placement agent
- Intermediating investment transactions
However, certain exemptions for having a CMS licence for dealing in capital markets products are available if:
- Marketing funds only to institutional investors
- Products are structured as bonds and only offered to certain investors
Limited exemptions for licensed fund managers
Singapore also provides limited exemptions where marketing activities are incidental to fund management.
These exemptions may apply in circumstances where:
- A Singapore-licensed manager is raising capital for its own funds or those managed by its related corporations
- Fundraising occurs in connection with segregated mandates
- Third-party fund investments form part of discretionary portfolio management
However, these exemptions are generally not available to offshore managers conducting fundraising activity independently.
Public offerings and available fundraising exemptions
Like Hong Kong, Singapore operates a prospectus regime for public fund offerings.
Public distribution generally requires authorisation or recognition by MAS unless a specific exemption applies.
Most U.S. alternative managers therefore rely on non-public offering exemptions.
Institutional investor exemption
One of the most significant exemptions available to foreign managers applies when offers are made exclusively to institutional investors.
Where this exemption applies:
- MAS authorisation is not required
- Recognition requirements do not apply
- A prospectus is not required
This exemption is widely used by managers targeting institutional allocators only.
Restricted Foreign Scheme regime
Another important fundraising pathway for offshore funds is the Restricted Foreign Scheme regime.
Under this structure:
- A private placement memorandum filing is submitted
- Registration is completed through a notification process
- Processing is typically straightforward
- Eligible funds are included on the MAS website
In practice, many private banks prefer foreign funds to have completed this process before agreeing to distribute them to clients.
For managers seeking access to Singapore’s wealth management ecosystem, this can become an important commercial consideration.
Private placement exemptions
Singapore also provides private placement exemptions for:
- Limit to 50 investors offered within a period of 12 months
- Fundraising below prescribed thresholds
However, managers should approach these exemptions carefully and ensure that all distribution materials contain the required Singapore-specific selling restrictions and investor eligibility disclosures.
The use of advertising is generally prohibited under these arrangements.
Understanding investor classifications in Singapore
Investor classification is central to fundraising compliance in Singapore.
Institutional investors
Key categories of institutional investors include:
- Government and sovereign-related entities
- Statutory boards
- Banks
- Insurance companies
- Licensed financial institutions
- Licensed trust companies
- Multilateral organisations
- Regulated foreign financial institutions
- Certain large entities designated by MAS
These investors benefit from significant regulatory exemptions under the Singapore fundraising framework.
Accredited Investors
Singapore also permits fundraising to Accredited Investors (AIs).
An individual may qualify as an AI through any one of the following criteria:
- Annual income of at least S$300,000
- Net personal assets exceeding S$2 million, with the primary residence capped at S$1 million for calculation purposes
- Net financial assets exceeding S$1 million
Corporate entities and trusts generally qualify where net assets exceed S$10 million and/or all controllers are AIs.
Why Accredited Investor status is unique in Singapore
One of the features that differentiates Singapore from many jurisdictions is that Accredited Investor status is not automatic.
Meeting the financial thresholds alone is insufficient.
The investor must actively opt in to Accredited Investor treatment and may subsequently opt out, and the investor can choose their status between the financial institutions.
This creates additional complexity for alternative investment managers, particularly those seeking to raise capital from private investors and family offices.
Managers should avoid assuming that all financially eligible investors have elected to be treated as Accredited Investors.
Cross-border fundraising and reverse solicitation
Singapore’s regulatory framework applies to offerings made both within Singapore and from outside Singapore.
The fact that a manager is located offshore does not automatically remove potential regulatory obligations.
There are, however, circumstances where an offshore manager may fall outside the licensing perimeter.
Examples may include:
- No physical presence in Singapore
- No Singapore-based marketing personnel
- Limited investor contact
- Genuine reverse solicitation situations
- Fundraising conducted through appropriately licensed intermediaries
These arrangements require careful analysis and should not be treated as blanket exemptions.
MAS and the growing importance of operational substance
Perhaps the most important trend affecting foreign managers today is MAS’s increasing emphasis on operational substance.
Historically, some firms viewed Singapore primarily as a fundraising location.
That approach is becoming increasingly difficult.
MAS is reluctant to license foreign managers whose Singapore operations are intended purely for fundraising purposes. Rather, MAS expects meaningful investment management activity and appropriately qualified investment professionals to be located in Singapore.
In simple terms, Singapore is no longer supportive of “fundraising shell” operations.
IQ-EQ’s experience: where managers encounter challenges
Having supported many global asset managers entering Asia-Pacific markets, several recurring themes emerge in Singapore.
Alignment of proposed personnel and business plan
Managers often face difficulty putting in place the right personnel with experience aligned to their roles in the Singapore entity’s proposed business activities, taking into consideration the operational substance requirement.
There is also the need to consider proportionality, i.e. whether the intention to commence more than one regulated activity or running multiple strategies / asset classes at the beginning is commensurate with the proposed number of qualified personnel.
Digital marketing risks
Managers also increasingly rely on:
- Webinars
- Virtual presentations
- Digital roadshows
- Online content
While highly effective commercially, these activities may create regulatory issues if they are accessible to Singapore investors and are viewed as active marketing.
Successful managers take a long-term approach to Singapore
In our experience, managers that achieve the strongest outcomes in Singapore generally:
- Develop regulatory and fundraising strategies together
- Invest in governance and operational infrastructure
- Build relationships before pursuing capital
- Establish clear investor segmentation frameworks
- Demonstrate genuine commitment to the market
The most successful firms typically view Singapore as a strategic regional platform rather than simply a fundraising destination.
Key takeaways
Singapore remains one of the most attractive institutional fundraising markets in Asia-Pacific. The combination of sovereign capital, institutional allocators, family offices and private banking platforms creates significant opportunities for U.S. managers.
However, fundraising success increasingly depends on understanding Singapore’s regulatory expectations around licensing, investor classification and operational substance.
Managers should:
- Understand CMS licensing implications
- Carefully assess investor classifications
- Consider the Restricted Foreign Scheme regime
- Evaluate distribution through private banks
- Monitor substance expectations when establishing a local presence
- Build fundraising strategies around long-term regional objectives
The managers that succeed are typically those that combine strong investment capabilities with disciplined governance, appropriate distribution structures and a genuine commitment to the Singapore market.
How IQ-EQ can help
Singapore offers significant opportunities for managers seeking institutional and private wealth capital across Asia-Pacific, but access often depends on getting the licensing, operating model and compliance arrangements right from the outset.
IQ-EQ supports managers with market-entry planning, CMS licensing considerations, outsourced compliance, fund administration, governance and operational infrastructure.
Drawing on extensive experience supporting alternative investment managers across Asia-Pacific, we help firms establish a practical regulatory and operating framework for fundraising in Singapore.
Get in touch today to learn more.
More from this article series
Click below to explore the main fundraising considerations in other key APAC markets: