Part of the IQ-EQ series: Raising institutional capital in Asia-Pacific
At a glance
Why ASEAN matters
ASEAN continues to benefit from favourable demographic, economic and wealth creation trends.
The region has experienced sustained GDP growth, growing middle-class populations and increasing institutionalisation of capital pools. These developments have created long-term opportunities for alternative asset managers seeking diversification beyond the more established fundraising markets in North Asia and Australia.
However, ASEAN is fundamentally different from markets such as Japan or Australia.
The institutional investor base remains smaller and more fragmented. Domestic investment priorities, regulatory restrictions and developing private markets ecosystems often influence capital allocation decisions. In many cases, local institutions remain heavily focused on domestic markets and local currency investments.
As a result, fundraising opportunities exist, but managers must generally adopt a more targeted and relationship-oriented approach.
ASEAN is not a single fundraising market
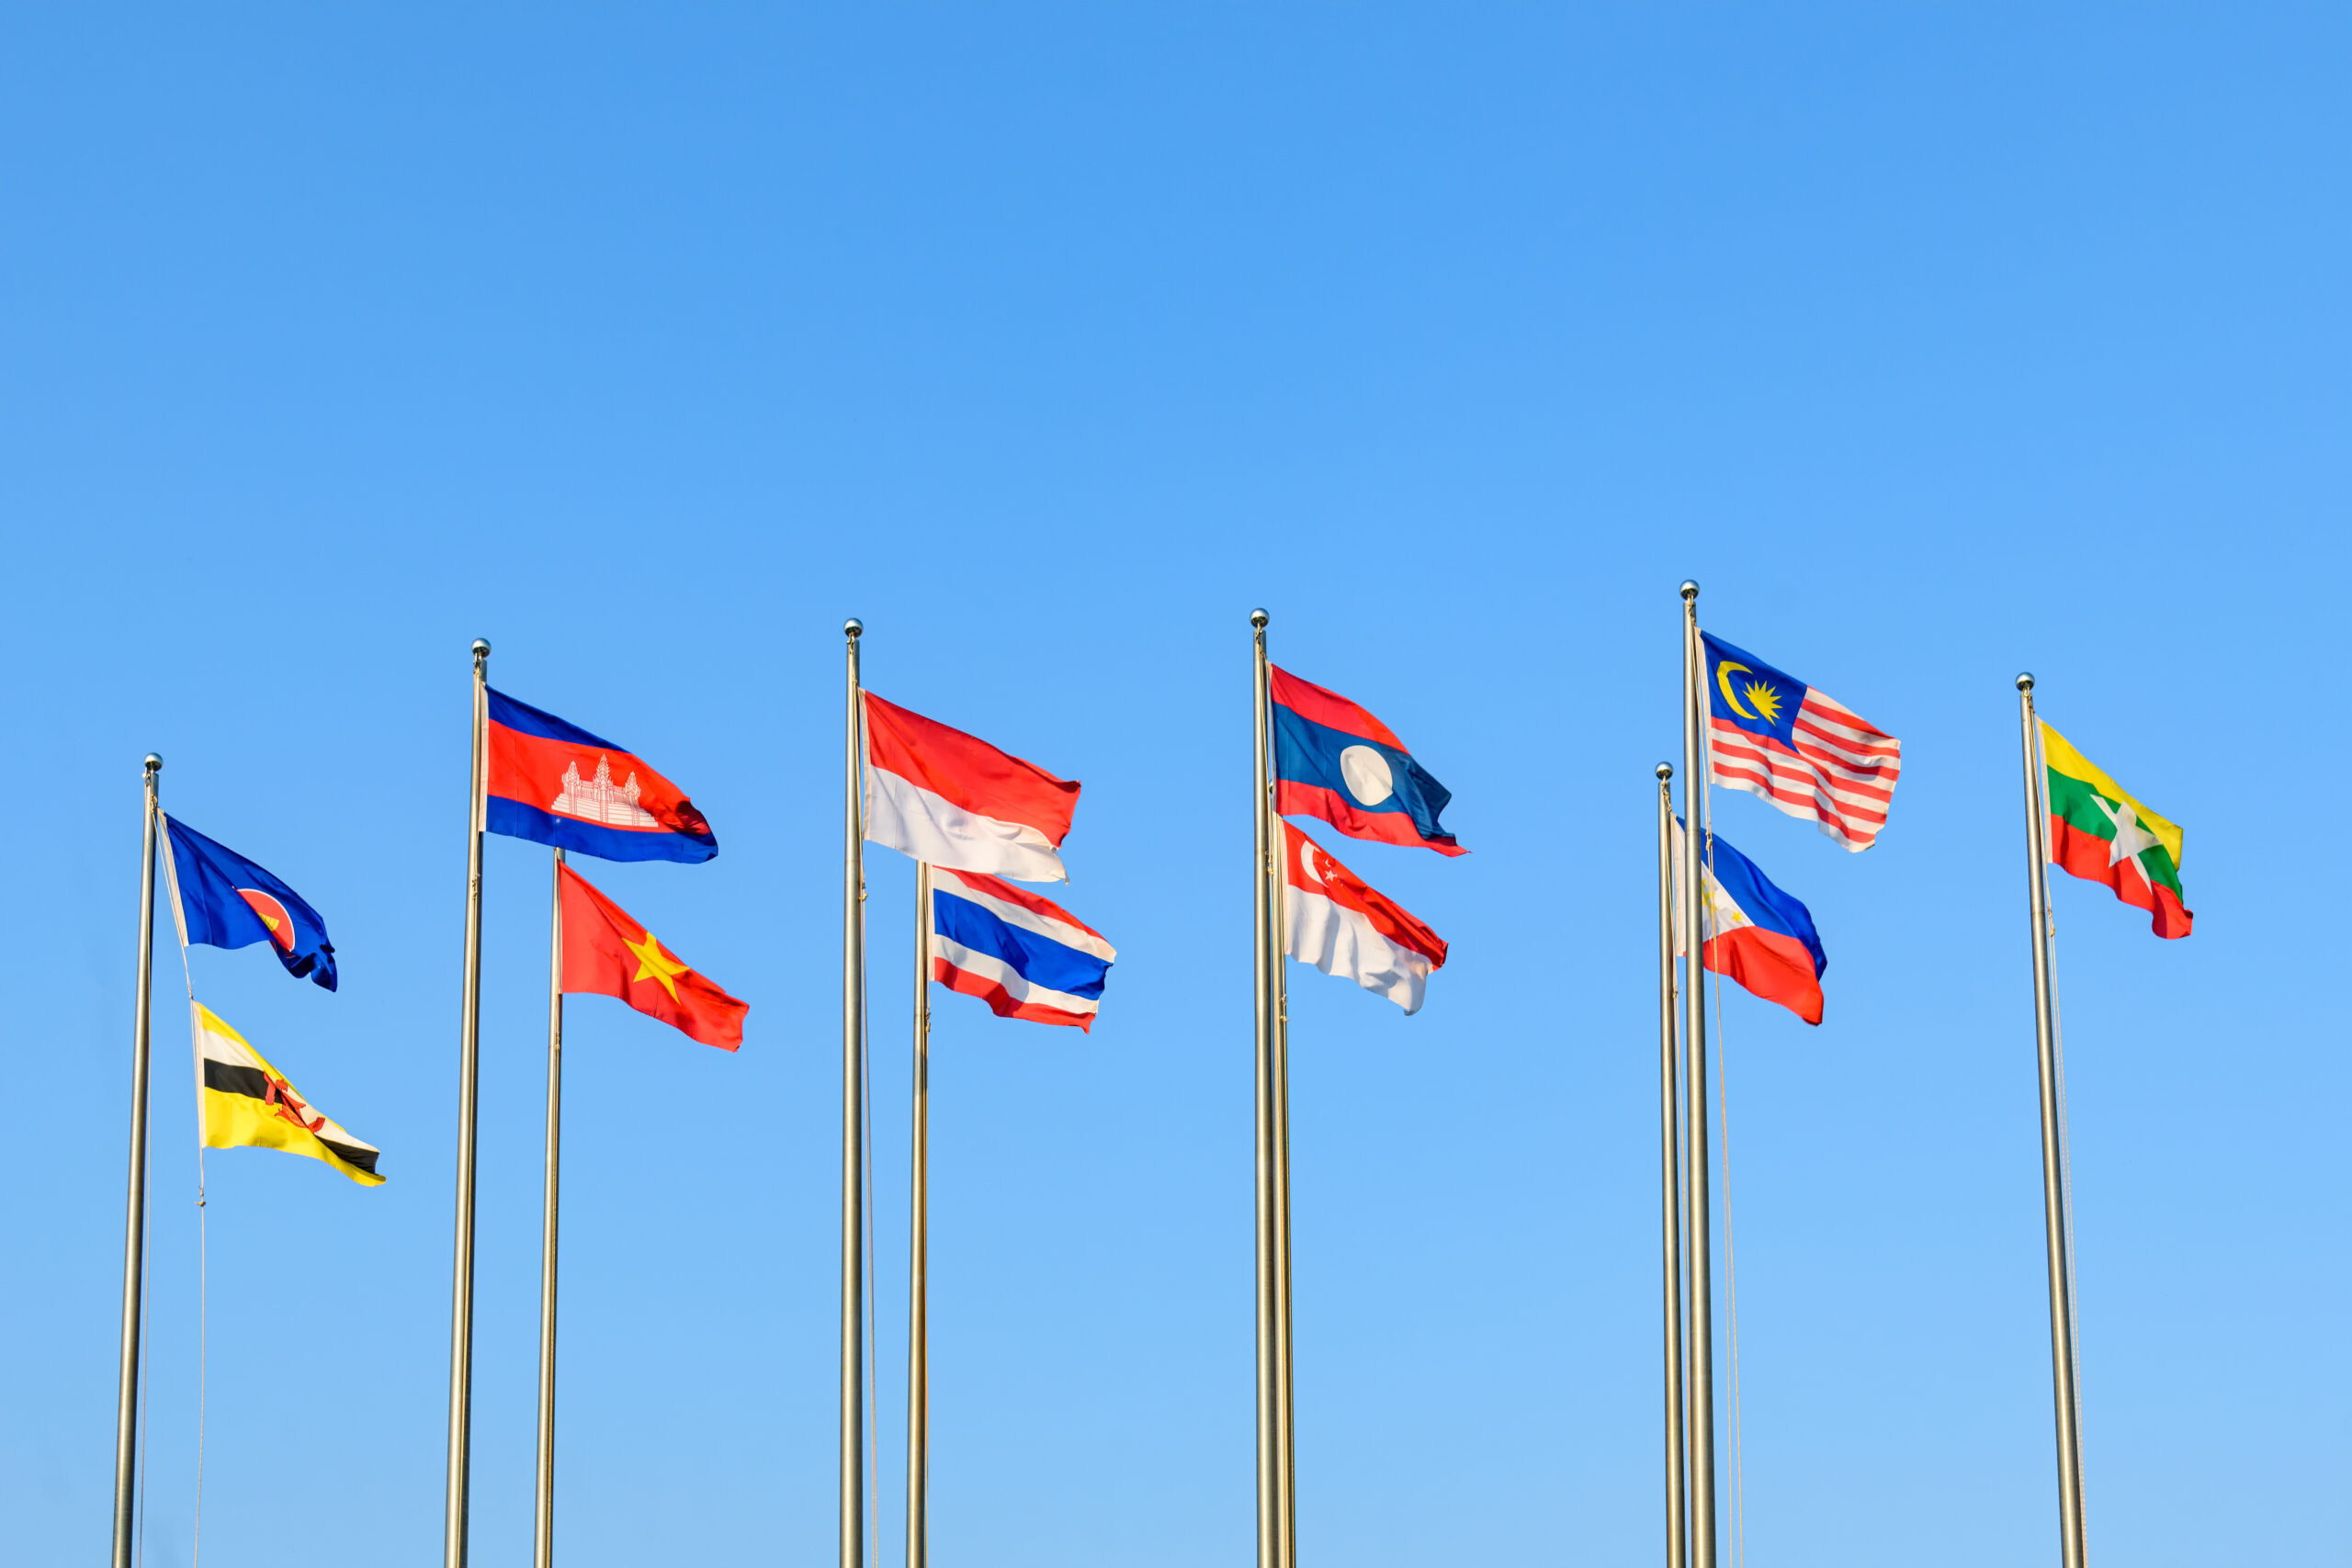
One of the most common mistakes made by first-time entrants is treating ASEAN as if it were a single capital market.
In reality, each jurisdiction has its own:
- Regulatory framework
- Licensing requirements
- Distribution model
- Institutional investor base
- Political environment
- Investment culture
A fundraising strategy that works effectively in Singapore may not be appropriate in Indonesia or Thailand. Similarly, investor expectations in Malaysia may differ significantly from those of Korean or Japanese institutions.
Successful managers therefore tend to assess each ASEAN market independently and develop jurisdiction-specific engagement strategies.
Understanding the ASEAN investor landscape
The role of sovereign wealth funds across ASEAN
Compared with the larger APAC fundraising markets, the ASEAN institutional landscape is relatively concentrated. Sovereign and government-linked investors remain among the most important sources of institutional capital.
Depending on the jurisdiction, these entities may include:
- Sovereign wealth funds
- Government pension funds
- State-linked investment corporations
- Government-controlled insurance pools
Access to these organisations is generally relationship-driven and often requires extensive engagement before formal fundraising conversations commence.
Many managers therefore focus first on establishing credibility and long-term market presence before pursuing significant fundraising opportunities.
Family offices: often managed outside their home markets
An important consideration for alternative investment managers is the location of family office activity.
While significant private wealth exists throughout ASEAN, many family offices are not managed from their country of origin. Instead, family office structures are frequently established in Singapore, regardless of where the underlying families or businesses are based.
As a result, managers seeking family office capital across Southeast Asia often discover that many conversations ultimately occur in Singapore rather than in local ASEAN markets.
This reinforces Singapore‘s role as a regional wealth management hub while highlighting the interconnected nature of ASEAN capital flows.
Malaysia: an established institutional market
Among ASEAN jurisdictions, Malaysia is often viewed as one of the more developed institutional fundraising markets.
The country benefits from several large and sophisticated investors, including:
- Employees Provident Fund (EPF)
- Khazanah Nasional
- Insurance companies
- Domestic asset managers
- Government-linked investment entities
These institutions have developed meaningful exposure to international investment opportunities and continue to participate in alternative asset classes.
Understanding Malaysian fundraising dynamics
Unlike some regional markets where institutional relationships are highly intermediary-driven, Malaysian investors often engage directly with managers through established networks and formal investment processes.
For foreign managers, fundraising opportunities commonly arise through:
- Co-investment opportunities
- Requests for proposal (RFPs)
- Existing institutional relationships
- Reverse solicitation scenarios
Many of these relationships are managed from Singapore, reflecting the close connections between the two markets.
Sharia considerations
Malaysia remains a global centre for Islamic finance.
While Sharia-compliant structuring considerations are often most relevant for domestic investment mandates, managers should understand that certain investors may require specific fund structures or investment approaches to satisfy internal requirements.
For firms targeting Malaysian capital, understanding investor-specific requirements early in the fundraising process can help avoid later structuring complications.
Indonesia: opportunities through partnerships
Indonesia represents one of Southeast Asia’s largest economies and continues to attract significant investor interest.
However, cross-border fundraising can be more complex than in some neighbouring jurisdictions.
Local partnerships often matter
Indonesia continues to favour local partnerships and collaborative investment approaches.
As a result, foreign managers frequently access opportunities through the following avenues rather than relying on traditional fund distribution models:
- Local asset management partnerships
- Co-investment arrangements
- Joint investment structures
- Partnerships with state-linked institutions
Administrative considerations
Cross-border activity can also involve significant administrative and regulatory requirements. Managers should therefore approach Indonesia with realistic expectations regarding timelines, documentation requirements and approval processes.
For many firms, Indonesia becomes a relationship-building exercise before it becomes a fundraising exercise. Strong local partnerships often play a decisive role in determining long-term fundraising success.
Thailand: distribution-led fundraising
Thailand has developed a substantial domestic investment market and continues to support both public and private investment activity.
However, access for foreign managers is often achieved through structured distribution mechanisms rather than direct fundraising models.
Local distributors remain important
Foreign fund distribution in Thailand often requires managers to work with:
- Licensed distributors
- Local asset managers
- Local feeder fund structures
These arrangements enable offshore strategies to access Thai investors while meeting local regulatory requirements.
Fundraising through local investment channels
Rather than marketing directly, many foreign managers participate in Thailand through locally established investment platforms and structures.
This reflects Thailand’s preference for regulated distribution pathways and highlights the importance of selecting appropriate local partners when entering the market.
Managers seeking long-term fundraising success in Thailand often focus significant effort on identifying distribution partners capable of supporting institutional investor engagement.
Why relationships matter more in ASEAN
One theme consistently differentiates ASEAN from several larger APAC fundraising markets:
Relationships are often the primary determinant of success.
While institutional due diligence, governance and regulatory compliance are important, access frequently depends on trusted local networks and long-term relationship development.
Managers entering ASEAN often find that investor introductions, local partnerships and established reputations carry significant weight when compared with purely distribution-led fundraising strategies.
As a result, market entry plans should incorporate relationship-building objectives alongside traditional fundraising activities.
IQ-EQ’s experience: relationships remain the differentiator
Having supported managers raising capital across Asia-Pacific, we consistently observe that ASEAN differs from more mature fundraising markets.
Unlike Australia, Japan or South Korea, fundraising opportunities often emerge through a smaller number of institutional relationships and personal networks.
The most common approaches used by foreign managers include:
- Reverse solicitation opportunities
- Existing institutional relationships
- Relationship managers with sovereign wealth fund connections
- Partnerships with local market participants
These approaches frequently generate better results than broad-based fundraising campaigns.
Managers that view ASEAN as a relationship market rather than a volume fundraising market are generally better positioned to identify opportunities and build sustainable investor relationships over time.
Key takeaways
ASEAN offers compelling long-term opportunities for U.S. alternative investment managers, but the region requires a different approach from the more developed fundraising markets of Asia-Pacific.
Before entering ASEAN markets, managers should:
- Treat each jurisdiction separately
- Understand local regulatory requirements
- Develop strong local relationships
- Evaluate partnership opportunities
- Consider distribution requirements carefully
- Adopt realistic fundraising timelines
- Focus on long-term market development
The most successful managers are typically those that combine a differentiated investment strategy with local market knowledge, trusted relationships and a patient approach to building institutional credibility.
How IQ-EQ can help
Fundraising across ASEAN requires careful navigation of market-specific licensing requirements, distribution arrangements, investor expectations and compliance obligations.
IQ-EQ supports alternative investment managers throughout their Asia-Pacific growth journey, helping firms evaluate market-entry strategies, outsourced compliance support, fund operations and local operating models.
Drawing on experience supporting managers across the region, we help clients put the practical arrangements in place to access institutional capital opportunities across Southeast Asia.
More from this article series
Click below to explore the main fundraising considerations in the more established APAC markets: